Salary Budgeting Guide
How to Build a Salary Budget from Scratch
A salary budget starts as a list of people and ends as a defensible number. This guide walks the sequence in the order you'll actually do it.
Start here
Start with the roster, not the total
Before any percentage assumptions, list every current employee with their base salary and expected changes for the period. Add planned hires with realistic start dates, because a hire in month eight costs roughly a third of a full year. A salary budget is a plan for the pay fund, and the plan is only as good as the roster underneath it.
If your roster lives in a payroll system, pull it from there rather than rebuilding it. Payroll data already reflects what people are actually paid, including mid-year adjustments and terminations that a spreadsheet copy would miss.
-
01
Pull current employees
Base salary, department, location, and pay frequency from payroll — not from a stale HR export.
-
02
Add expected changes
Promotions, transfers, and known departures with their effective dates inside the budget period.
-
03
Layer planned hires
Month of start, target salary, and whether the role is backfill or net-new headcount.
-
04
Reconcile against payroll
Compare the roster total to your last payroll run. A mismatch means the roster is missing someone.
One working station, the same scene every month — the roster underneath the number.
Salary budget review
Merit increases are usually funded as a pool before individual decisions are made. The pool size depends on your market position, your budget constraints, and how many employees are eligible in the cycle. Not everyone is: recent hires, people on performance plans, and employees above range often sit out.
Eligible group
Employees past their first review cycle and within range for their band.
Usually excluded
Recent hires inside their first cycle, employees on performance plans, and pay above band maximum.
Paycom's compensation budgeting tool handles this by applying performance review ratings and merit matrix values automatically — the same logic you'd apply manually. Decide your eligibility rules before you set the percentage, or the pool and the actual increases won't match.
Merit cycles
Set the merit increase pool
A merit pool is a percentage of eligible base pay, not a flat sum. Get the denominator right first — total payroll is the wrong base, because it includes people who won't receive an increase this cycle.
Then decide when the increase takes effect. A cycle that starts in July costs half of an annualized pool, and that timing is where most first drafts drift from the approved number.
Load employer payroll taxes
Base salary is not your cost. Employer payroll taxes add a layer that varies by state and by wage base, and it applies to every dollar of taxable pay. PlanGuru mentions payroll tax modeling as a feature, and Prophix One includes calculations for salary, wages, and taxes together, because in practice you can't forecast one without the other.
If you're doing this by hand, apply your rates to projected taxable wages per employee, not to the department total. Wage bases cap out at different points for different people, and a department-level rate hides that.
Add benefits cost
Benefits are usually budgeted per employee rather than as a percentage, since health premiums don't scale with salary. Pull your employer contribution per plan tier and multiply by enrollment, then add the cost of any new hires who become eligible.
This is the line item most likely to be underestimated, because eligibility waiting periods and mid-year plan changes shift the timing. Neubrain treats benefits as one of several layers alongside salary, inflation, and vacancy adjustments, which is the right mental model: benefits are a distinct cost stream, not a rounding addition to salary.
Project overtime and variable pay
Overtime, shift differentials, bonuses, and commissions are part of labor spend even when they're not part of base pay. Historical overtime as a percentage of regular wages is a reasonable starting point, adjusted for any known changes in staffing or production.
For bonuses, use your plan's target and your expected attainment, not last year's payout. Leaving variable pay out of the budget doesn't make it disappear. It just moves the surprise to a later variance report.
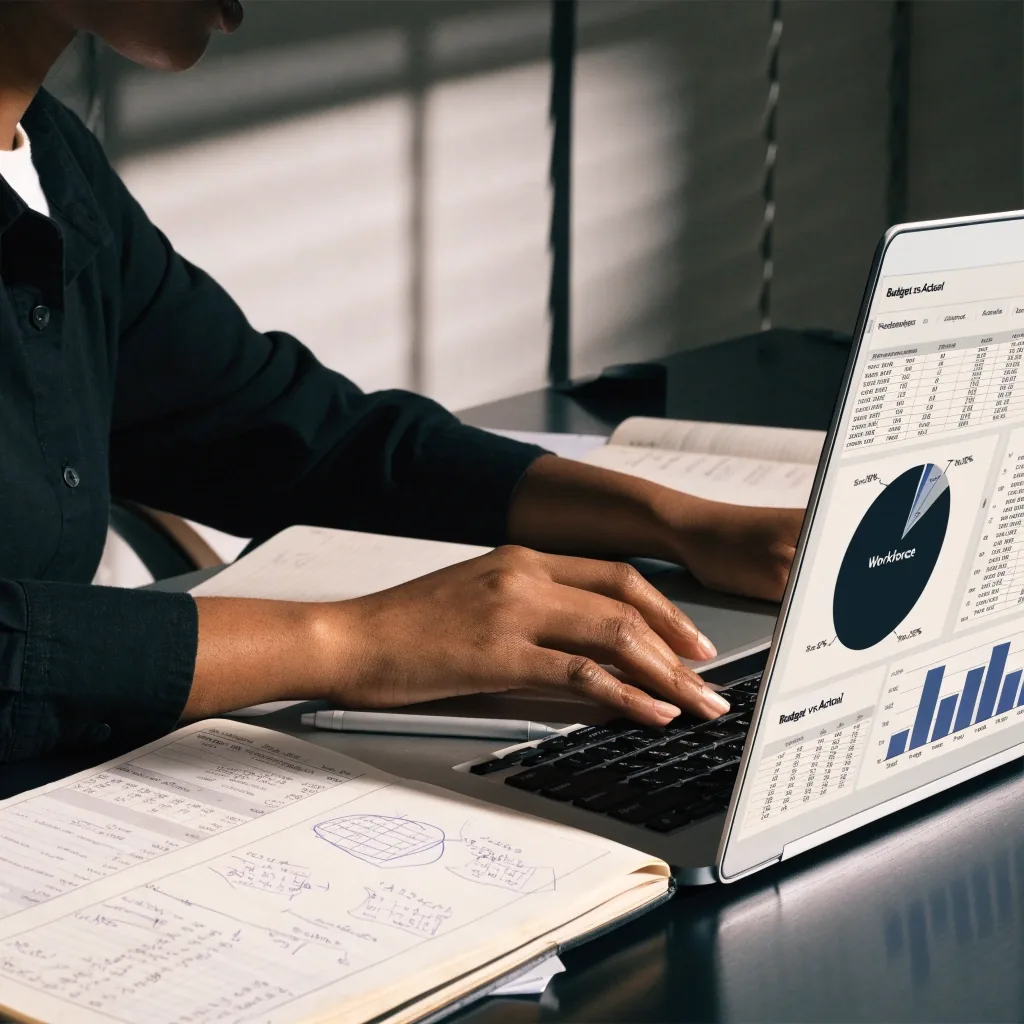
Budget versus actuals
The goal isn't a perfect forecast. It's knowing why the number moved.
Once the budget is approved, the monthly work begins: comparing what you planned to what you spent, and explaining the gap. Variances usually come from timing (a hire started late), from rate changes you didn't forecast, or from overtime that ran higher than planned.
Track them by category so the explanation is specific. A monthly or annual forecasting cadence, which Eddy references, keeps the comparison current instead of annual. One number off by a plausible cause beats a summary that says only that the total was high.
Timing variance
A hire started later than planned. Cost is real but shifted, not saved.
Rate variance
Pay rates, tax rates, or benefit contributions changed after the budget was approved.
Volume variance
Overtime or variable pay ran higher than the plan assumed for the same headcount.
Where the plan meets its limit
When a spreadsheet stops working
Spreadsheets are fine for a small team with one planning cycle. They break when multiple people need to edit, when you're running several hiring scenarios, or when finance wants to see the budget recalculated under different assumptions. At that point, planning software earns its cost. The signal is usually a version-control problem: two people editing the same file, or a scenario that exists only in someone's head.
More than one person edits the plan, and version control becomes a conversation instead of a file state.
Hiring scenarios multiply — three headcount paths with different start dates and different tax implications.
The budget needs recalculation when assumptions change, and doing it by hand takes longer than the meeting it informs.
Finance and HR need shared visibility, so the plan can't live on one analyst's machine.
A monthly cadence turns the budget from a document into a working comparison. Same file, same roster, new actuals — and one short note on what changed.
What to prepare
- Payroll register for the closed period
- Roster changes since the last review
- Overtime and variable pay by department
- Any rate or benefit tier changes
Tools mentioned in this guide
Different platforms solve different parts of the salary budgeting job. These are the products referenced above, with what each one is typically used for — compare them on the detail that matters to your cycle.
Workday Adaptive Planning
Used by finance teams that model salary, wages, and taxes in one plan. Suited to organizations where payroll tax and benefits cost sit in the same model as headcount.
Best fit when
You need payroll tax and benefits modeled alongside salary, not bolted on afterward.
Paycom Compensation Management
Applies performance review ratings and merit matrix values to the pool automatically, so eligibility rules and the increase budget stay in step.
Best fit when
Your merit cycle is matrix-driven and you want the pool calculated from the same rules you apply manually.
Visier Workforce Planning
Builds hiring scenarios against the workforce plan, so a change in start dates or department mix shows up in the budget total before the cycle closes.
Best fit when
You run several headcount scenarios and need each one priced before you commit.
Neubrain Pay and Personnel Budgeting
Treats benefits as a distinct cost layer alongside salary, inflation, and vacancy adjustments — useful when benefits are the line item that keeps drifting.
Best fit when
Benefits cost is a separate stream in your model, not a percentage added to salary.
Questions teams ask first
The three answers below cover the points that come up most often when a salary budget is built for the first time.
How far ahead should a salary budget be built?
Most US organizations build annually, sometimes with a mid-year reforecast. Monthly and annual forecasting, as Eddy describes, keeps the plan connected to actuals rather than freezing it for twelve months.
Should the merit pool include payroll taxes?
Yes. Merit increases raise taxable wages, so employer payroll taxes rise with them. If you fund the pool without the tax layer, the budget understates the true cost of the cycle.
Do I need software to build a salary budget?
Not always. A single planner with a stable roster can manage in a spreadsheet. Software becomes worthwhile when you need employee-level labor cost modeling, multiple scenarios, or shared access across HR and finance.
Build the plan once, then keep it current
A salary budget that stays useful is one that gets revisited — roster changes, merit decisions, tax rates, and benefit tiers all move during the year. If you're still building your first draft, start with the roster and work down the cost layers in order.
Abensio — 1201 North Market Street, Suite 111, Wilmington, DE 19801, USA · +1-302-555-0148 · [email protected] · Monday to Friday, 9:00 AM – 6:00 PM ET